All about AFRMM

gonzaga • 24 de junho de 2024

The AFRMM (Additional Freight Charge for Renewal of the Merchant Marine): An Essential Tax in Brazilian Foreign Trade

This article aims to provide a comprehensive overview of AFRMM, addressing its definition, calculation, applicable legislation, taxable events, exemptions, suspensions, and payment procedures.

Our goal is to clarify common doubts among freight forwarders and customs brokers, offering essential information for efficient import operations management.

What is AFRMM?

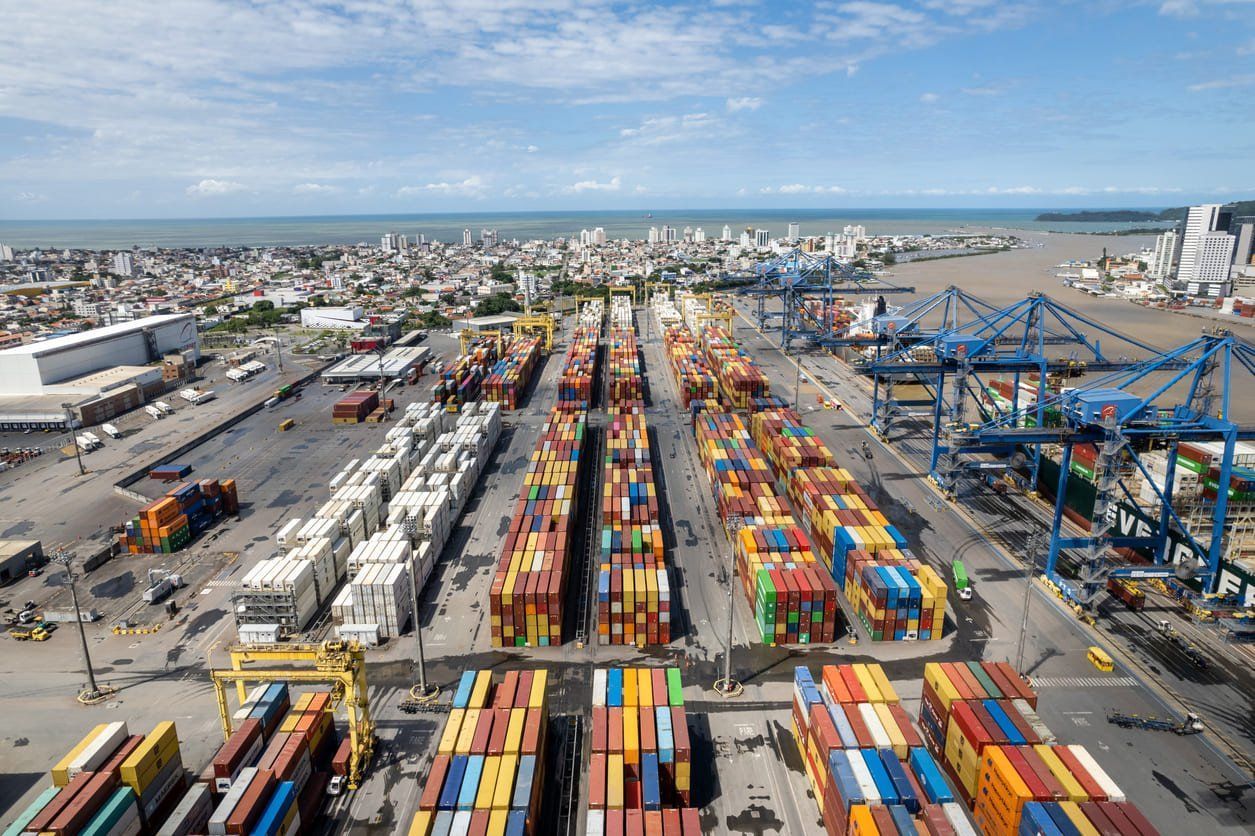
AFRMM is a tax levied on the freight cost of waterway transport operations conducted by vessels operating in Brazilian ports.

Established by Decree-Law No. 2,404/1987 and regulated by Law No. 10,893/2004, AFRMM aims to finance the Merchant Marine Fund (FMM), supporting the development of the merchant marine and the shipbuilding and repair industry in Brazil.

This tax is administered by the Federal Revenue Service of Brazil (RFB), responsible for its collection, inspection, and enforcement.

According to the RFB, the taxable event for AFRMM occurs when the unloading operation of a vessel begins at a Brazilian port, encompassing both long-haul navigation and cabotage as well as river and lake navigation.

The owner of the transported cargo is jointly responsible for the tax payment, which must be made before the nationalized goods are received.

How to Calculate AFRMM

AFRMM is calculated based on the cost of waterway transport, with varying rates depending on the type of navigation:

  • 8% for long-haul navigation and cabotage.
  • 40% for river and lake navigation transporting liquid bulk cargo in the North and Northeast regions.
  • 8% for solid bulk cargo and other loads in the same regions.

These rates have undergone changes over time, with the rate reduced to 8% after the enactment of Law No. 14,301/22. The RFB advises that AFRMM calculation and payment should follow the rate in effect on the payment date, with any outstanding balances adjusted via DARF.

AFRMM: Applicable Legislation

The main legislation regulating AFRMM is Law No. 10,893/2004, supplemented by various ordinances and decrees that outline the conditions for collection, exemption, suspension, and reimbursement of the tax.

Recently, Law No. 14,366/2022 introduced significant updates, including the reinstatement of AFRMM exemptions for companies using the Drawback Exemption regime.

AFRMM administration falls under the jurisdiction of the Federal Revenue Service, as regulated by Decree No. 8,257/2014, which provides administrative procedures for the tax's collection and inspection.

What is the Taxable Event for AFRMM?

The taxable event for AFRMM is the actual start of the vessel's unloading operation at a Brazilian port. This operation can result from long-haul (international) navigation or cabotage and river/lake navigation (domestic).

It’s important to note that the tax is due regardless of the customs regime to which the goods are subject, and it is the cargo owner's responsibility to ensure payment before releasing the goods.

Exemptions, Suspensions, and Non-Incidence Cases

There are several scenarios in which AFRMM exemptions or suspensions may apply. Companies benefiting from special customs regimes, such as Drawback Suspension, the Industrial Warehouse Regime under Computerized Control (Recof), and Temporary Admission, may request a suspension of the tax.

Additionally, products intended for scientific research, non-commercial samples, and other specific purposes may be exempt.

Requests for exemption or suspension should be submitted through the Federal Revenue’s Mercante System, preferably before filing the Import Declaration (DI).

Non-incidence of AFRMM is automatically applied by the system in certain legal situations, such as for goods transported under the customs transit regime.

Where and How to Pay AFRMM

AFRMM must be paid before registering the Import Declaration (DI), although it can also be paid afterward. Taxpayers should access the Mercante System to generate the Federal Revenue Collection Document (DARF) for the tax.

Recently, the Federal Revenue replaced the collection document from GRU to DARF, eliminating the previous R$1.20 bank fee. This change aims to simplify the payment process and the remuneration of the collection agent, as per the conditions established by Ordinance MF No. 479/2000.

Conclusion

AFRMM is a critical tax for funding Brazil's merchant marine and shipbuilding industry. Understanding its application, calculation, and governing legislation is fundamental for freight forwarders and customs brokers working in foreign trade.

By staying informed about exemptions, suspensions, and payment procedures, these professionals can ensure more efficient and cost-effective import operations management.

Additionally, it’s crucial to understand the relationship between AFRMM and other charges in foreign trade, such as demurrage, which is the fee for extra time using a container or vessel beyond the contracted period. Knowing these aspects helps avoid unexpected costs and surprises in logistics operations.

Did you enjoy this article on AFRMM and how it works? Subscribe to our blog for more updates on foreign trade!

Conheça mais

Continue a navegar no blog da Allink

23 de setembro de 2026
Os portos de Santa Catarina são referência para o Brasil. Isso significa que há um impacto direto desses portos na logística e na economia brasileira, já que 70% dos produtos entram e saem do Brasil por via marítima.  Em uma faixa litorânea de 531 km, o estado de Santa Catarina apresenta uma das melhores estruturas portuárias do país, com cinco portos de significativa relevância local e nacional. Muitas empresas optam pelos portos de Santa Catarina pelo posicionamento estratégico entre o sul e o sudeste, bem como devido aos incentivos fiscais recebidos. Um exemplo desses benefícios é o TTD 409 , que garante vantagens como diferimento do ICMS, diferimento parcial na operação interna subsequente à importação e, por fim, crédito presumido. Surgem, no entanto, dúvidas comuns sobre a estrutura desses portos, sobretudo para quem não conhece a realidade catarinense. Neste artigo, vamos mostrar em detalhes algumas das principais características dos portos de Santa Catarina.
23 de setembro de 2026
The ports of Santa Catarina are a reference for Brazil. This means that there is a direct impact from these ports on logistics and the Brazilian economy, as 70% of products enter and leave Brazil via maritime routes. Along a 531 km coastline, the state of Santa Catarina boasts one of the best port infrastructures in the country, with five ports of significant local and national relevance. Many companies choose the ports of Santa Catarina for their strategic positioning between the south and southeast, as well as due to the fiscal incentives offered. One such benefit is TTD 409, which provides advantages like deferred ICMS, partial deferral in the subsequent internal operation following importation, and, finally, presumed credit. However, common doubts arise about the infrastructure of these ports, especially for those unfamiliar with the reality of Santa Catarina. In this article, we will show in detail some of the main characteristics of the ports of Santa Catarina.
Por Carla Lima • 17 de setembro de 2026
Veja como a Golden Week chinesa impacta a logística marítima internacional, tanto em embarques e prazos quanto no planejamento de importadores e exportadores.
Mantenha-se informado(a) sobre o transporte marítimo internacional

Assine nossa newsletter e receba atualizações frequentes e de forma gratuita sobre o mundo da logística.